
A commercial property with an attractive asking price isn’t necessarily a good investment. A lower purchase price may reflect deferred maintenance, weak tenant demand, declining rental income, or problems that require substantial capital to resolve.
Successful property evaluation involves looking beyond the initial acquisition cost. Investors need to understand how an asset generates income, what risks could affect its performance, and whether its long-term potential justifies the financial commitment.
Before acquiring a multifamily, retail, industrial, or other commercial property, consider these seven factors that can influence investment performance.
1. Location and Long-Term Market Fundamentals
Location influences commercial property performance, but a desirable address alone doesn’t guarantee strong investment results.
Investors should examine the economic conditions supporting demand in a particular market. Employment opportunities, population trends, transportation access, infrastructure, and nearby development can all affect occupancy and rental potential.
Different property types also have distinct location requirements.
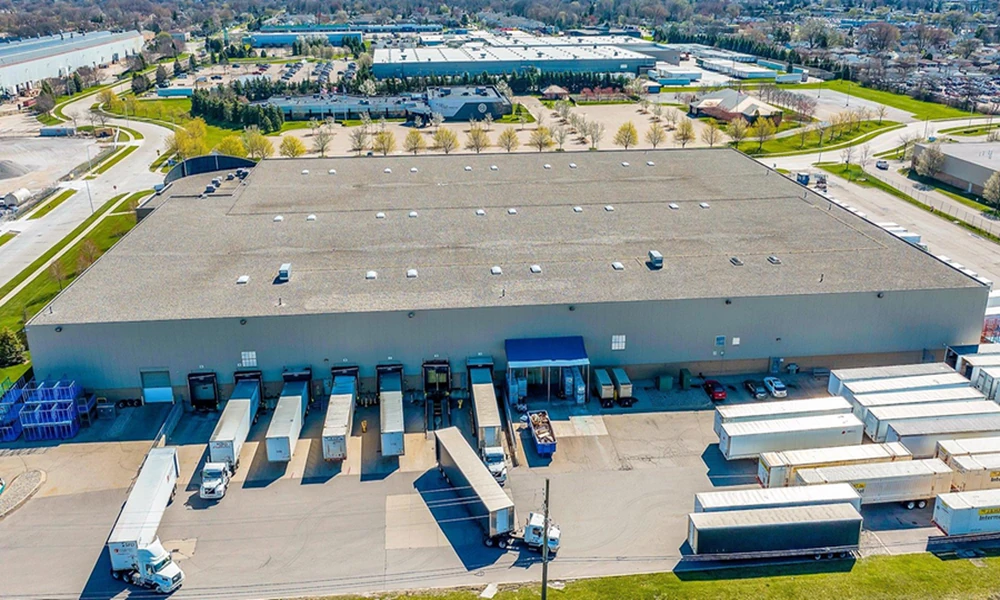
Multifamily communities depend partly on residential demand, employment access, and neighborhood amenities. Industrial properties may benefit from efficient highway connections and proximity to distribution networks. Retail assets often depend on accessibility, local demographics, and customer activity.
Evaluating the property within its specific market helps investors distinguish sustainable demand from temporary enthusiasm.
2. Net Operating Income and Cash Flow
A property’s income-generating ability is one of the most important considerations in commercial real estate investing.
Net operating income (NOI) represents property operating revenue minus operating expenses, excluding financing costs, income taxes, and certain capital expenditures.
Investors should evaluate existing rental income alongside recurring expenses such as maintenance, insurance, property taxes, utilities, and management fees.
It’s also important to distinguish actual financial performance from projected results.
An acquisition may appear attractive based on assumptions about future rental increases or lower operating costs. However, projected improvements should be supported by realistic market conditions and a practical operating plan.
Reliable historical statements, lease records, and operating budgets provide a stronger foundation for evaluating sustainable income.
3. Choosing the Right Investment Approach
Commercial properties offer different combinations of stability, growth potential, and management requirements.
A fully stabilized property with reliable occupancy and predictable income may appeal to investors seeking relatively consistent cash flow. An underperforming property may offer opportunities to increase value through renovations, improved management, leasing initiatives, or operational changes.
Neither approach is automatically superior.
The appropriate choice depends on available capital, investment objectives, risk tolerance, management capabilities, and the expected ownership period.
Understanding the difference between core and value-add approaches is an important part of developing a real estate investment strategy that matches a property’s existing condition with realistic opportunities for future improvement.
Investors should also consider how much active involvement an acquisition will require. A property needing extensive repositioning may offer meaningful potential, but that opportunity comes with additional execution risk.
4. Property Condition and Capital Expenditure Requirements
A property’s physical condition can significantly affect its financial performance after acquisition.
Deferred maintenance, outdated systems, structural problems, and inefficient building operations may create expenses that aren’t obvious from the listing price.
Before purchasing, investors should consider professional inspections and assessments of major building components, including roofing, electrical systems, plumbing, HVAC equipment, and accessibility features.
Capital expenditure planning should distinguish routine maintenance from major improvements.
For example, replacing an aging roof is different from renovating apartments to support higher rents. Both may require substantial funding, but their purposes and potential financial effects differ.
Investors should prepare realistic improvement budgets that account for unexpected expenses, project delays, and disruptions to property operations.
A clear understanding of physical conditions reduces the likelihood of discovering costly problems after closing.
5. Tenant Quality and Lease Structure
Tenant relationships directly influence the reliability of commercial property income.
A building with strong occupancy can still present financial risks if multiple leases expire within a short period or tenants have difficulty meeting their obligations.
Investors should examine tenant concentration, lease expiration schedules, payment histories, security deposits, and contractual responsibilities.
Commercial lease structures can also affect operating expenses and cash flow.
For instance, some leases require tenants to reimburse certain property expenses, while others leave a greater share of those costs with the property owner.
Multifamily investors should focus on occupancy trends, tenant turnover, achievable rents, and ongoing leasing costs.
Understanding lease obligations helps investors estimate both the stability of current income and the potential cost of maintaining occupancy.
6. Financing Terms and Downside Protection
A promising property can become a difficult investment when financing assumptions are overly optimistic.
Borrowing costs, loan maturities, repayment schedules, and lender requirements all influence the financial flexibility of an acquisition.
Investors should evaluate whether property income can support debt payments under different operating conditions.
Stress testing is particularly useful.
What happens if vacancy increases, rental growth slows, insurance costs rise, or a planned renovation takes longer than expected?
Potential refinancing challenges should also be considered, especially when the investment depends on securing new financing at a future date.
Maintaining appropriate cash reserves and using conservative financial assumptions can help reduce vulnerability to unexpected market changes.
7. Exit Strategy and Long-Term Flexibility
An investment shouldn’t depend entirely on selling the property at a higher price.
Before acquisition, investors should consider how the asset might perform under different ownership and market scenarios.
Possible outcomes include holding the property for ongoing income, refinancing after operational improvements, selling after stabilization, or maintaining ownership through a weaker market.
Each option has different financial implications.
Investors should assess expected holding costs, future capital requirements, potential buyer demand, and the conditions needed to execute an exit successfully.
An adaptable plan gives owners more options when market conditions change.
Rather than relying on one optimistic outcome, the investment should remain financially manageable across a reasonable range of scenarios.
Conclusion
Evaluating commercial real estate requires more than comparing asking prices or estimating future appreciation.
Market fundamentals, operating income, property condition, tenant stability, financing, and long-term flexibility all play important roles in determining whether an acquisition makes financial sense.
The strongest investment decisions are supported by thorough due diligence, realistic assumptions, and a clear understanding of the risks involved.
By examining these seven factors together, investors can better distinguish properties with sustainable potential from opportunities that depend too heavily on uncertain outcomes.